What is the scope and industry significance of the Management Consulting Services Market?
Our analysis indicates that the Management Consulting Services Market reaches an impressive $1178.03 Billion in 2026. This sector encompasses specialized advisory verticals—ranging from Operations Advisory to Technology Advisory—driving corporate restructuring and regulatory compliance across global enterprises.
Key market drivers, restraints, challenges, and opportunities shaping Management Consulting Services Market
Growth is accelerated by complex digital transformations and stringent regulatory mandates overseen by bodies like the SEC and European Union frameworks. However, firms face fee compression pressures and geopolitical volatility, creating critical opportunities in cloud migration and cybersecurity advisory.
The Shift Toward Digital and Sustainable Advisory
Industry trends show a decisive pivot toward Technology Advisory and Environmental and Sustainability Consulting. Clients increasingly demand integrated cloud infrastructure strategies alongside ESG governance compliance, favoring tech-forward practices over traditional legacy consulting models.
How did the COVID-19 pandemic impact the Management Consulting Services Market trajectory?
The pandemic initially disrupted face-to-face advisory engagements, forcing a rapid digitization of consulting delivery models. Our research shows this catalysed a permanent shift toward remote diagnostic tools, remote cloud architecture consulting, and agile crisis management frameworks.
Competitive Benchmarking and Industry Consolidation
The market features high competitive concentration led by giants such as Accenture, PwC, McKinsey & Company, and Boston Consulting Group. These firms leverage proprietary analytics and global delivery networks to outpace boutique competitors in large-scale enterprise transformations.
Executive Summary of the Management Consulting Services Market
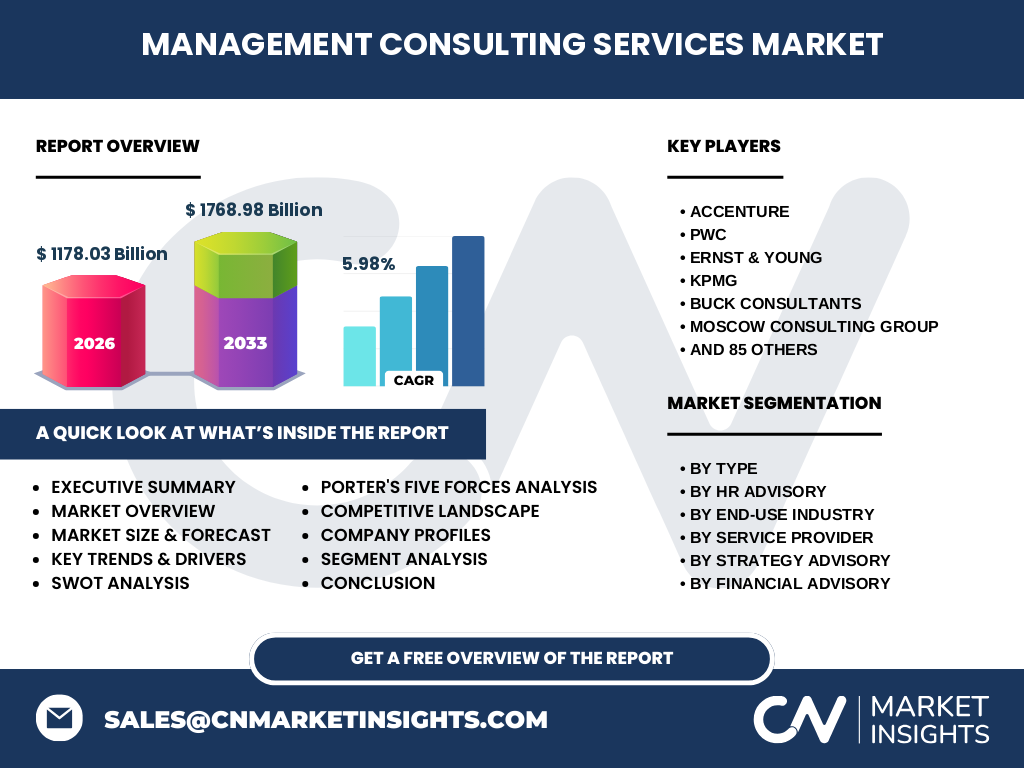
Valued at $1178.03 Billion in 2026, the Management Consulting Services Market is projected to expand significantly to $1768.98 Billion by 2033, registering a robust CAGR of 5.98% driven by widespread enterprise digitalization.
Market Forecast and Long-Term Growth Trajectory
Based on our econometric modeling, the market will scale from $1178.03 Billion in 2026 to $1768.98 Billion by 2033. This 5.98% CAGR reflects sustained corporate spending on mergers and acquisitions advisory and supply chain resilience.
Segmentation Analysis of Consulting Services
The market breaks down by type into Operations Advisory, Financial Advisory, Technology Advisory, Strategy Advisory, HR Advisory, and Other Consulting Services. Technology and Financial advisory capture the highest wallet share due to continuous software deployment and valuation needs.
Regional Market Analysis and Geographic Distribution
North America and Europe dominate the geographic landscape, supported by mature financial services ecosystems and rigorous corporate governance standards. Meanwhile, Asia-Pacific emerges as the fastest-growing regional frontier, fueled by rapid manufacturing and IT infrastructure expansion.
In-Depth Regional Review of North America and EMEA
North America anchors global demand through heavy enterprise technology adoption and massive private equity deal flows. Concurrently, EMEA markets navigate complex regional compliance regulations, boosting demand for specialized advisory from firms like Roland Berger and Oliver Wyman.
Strategic Positioning of Leading Company Profiles
Top-tier players like Deloitte, KPMG, and Ernst & Young combine multidisciplinary tax, audit, and strategic consulting under one roof. Meanwhile, specialized boutiques like L.E.K. Consulting carve out distinct advantages via deep industry-specific vertical expertise.
Porter's Five Forces Assessment of the Industry
Supplier power remains moderate due to the abundance of skilled human capital, whereas buyer power is high given intense rivalry among top-tier consulting firms. Threat of substitutes is mitigated by the highly customized, trust-based nature of strategic advisory mandates.
SWOT Analysis of the Consulting Landscape
Key strengths lie in unmatched intellectual capital and proprietary data assets. Weaknesses involve high dependency on billable hours. Opportunities thrive in Digital Transformation and ESG advisory, while macroeconomic slowdowns pose ongoing external threats.
Value Chain Analysis from Expertise to End-User
The value chain originates with raw intellectual capital and proprietary frameworks, flows through diagnostic analytics and strategic synthesis, and terminates in customized implementation for end-use industries like Financial Services and Manufacturing.
Investment Insights and High-Potential Opportunity Areas
Investors should target niche firms specializing in Cybersecurity And Risk Management Consulting and Supply Chain Management Consulting. These sub-segments exhibit superior margin resilience amid ongoing global logistical bottlenecks and data privacy legislation.
Conclusion and Strategic Takeaways for Stakeholders
Capturing future value in the Management Consulting Services Market requires proactive integration of advanced digital tools and sustainability frameworks. Firms failing to adapt risk margin erosion as enterprise clients demand quantified, technology-driven ROI.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining trade registry disclosures, primary stakeholder interviews with managing directors, and secondary macroeconomic indicators such as cross-border M&A volumes and enterprise software spending metrics.
Scope of the Report and Coverage Parameters
This report covers global market sizing from 2026 to 2033, evaluating service providers across large enterprises and SMEs. Limitations exclude informal freelance advisory engagements lacking institutional registry verification.
Recent Developments and Strategic Industry Moves
Recent market activities feature aggressive cross-border acquisitions and technology partnerships. Major players are actively integrating boutique AI analytics firms to bolster their proprietary technology advisory portfolios and outmaneuver macroeconomic headwinds.